
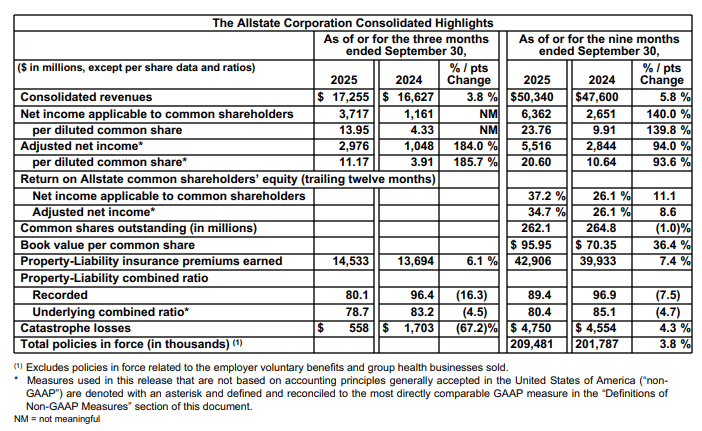
- Allstate Protection auto insurance results reflect execution of Transformative Growth, with strong margins and increased new business growth over the prior year.
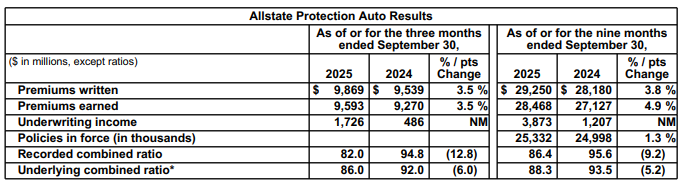
- Written and earned premiums grew 3.5% compared to the prior year quarter.
- Auto insurance rate increases resulted in an annualized premium impact of 0.6% in the third quarter, reflecting continued moderation in loss cost trends.
- Auto insurance policies in force continue to grow reflecting expanded distribution, increased marketing, new products and sophisticated rating plans. Policies grew by 1.3% as a 23.0% increase in new business was negatively impacted by lower customer retention. Active brand auto insurance polices grew by 2.8%, which was partially offset by decreases in legacy Esurance and Encompass policies.
- The recorded auto insurance combined ratio of 82.0 in the third quarter of 2025 was a 12.8 point improvement from the prior year quarter, reflecting higher average earned premiums, moderating loss costs and the benefit of non-catastrophe reserve releases.
- Prior year non-catastrophe reserve reestimates were $480 million in the third quarter, a 5.0 point benefit to the combined ratio, reflecting favorable severity development in personal auto injury and physical damage coverages.
- The underlying auto insurance combined ratio* of 86.0 in the third quarter of 2025 was a 6.0 point improvement from the prior year quarter, as growth in average earned premiums exceeded improving underlying loss and expense trends per policy. The third quarter underlying auto insurance combined ratio benefited from 2.4 points of favorable development on claims reported in the first and second quarters of 2025.
- Allstate Protection homeowners insurance generated strong returns and remains an attractive growth opportunity. Underwriting profit of $1.1 billion increased from $60 million in the prior year quarter, supported by lower catastrophes and excellent underlying margins.
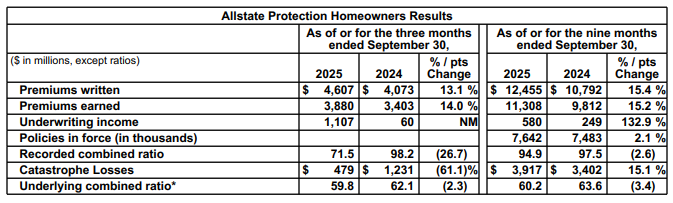
- Written premiums and earned premiums increased by 13.1% and 14.0% compared to the prior year quarter, respectively, due to higher average premiums and policy in force growth.
- A 12.0% increase in Allstate brand homeowners insurance average gross written premium compared to the prior year quarter reflects continued rate increases and higher home replacement costs.
- Policies in force increased 2.1% compared to the prior year quarter, primarily driven by 3.6% growth in Allstate brand homeowners insurance policies, offset by a reduction in National General legacy products.
- Catastrophe losses of $479 million in the quarter decreased $752 million compared to the prior year quarter due to fewer and less severe events as well as the absence of any hurricanes and tropical storms.
- The recorded homeowners insurance combined ratio of 71.5 was 26.7 points below the third quarter of 2024, due to lower catastrophe losses, higher average earned premiums and favorable non-catastrophe frequency trends.
- The underlying combined ratio* of 59.8 improved by 2.3 points compared to the prior year quarter, primarily driven by higher average premiums and favorable non-catastrophe loss trends.
