
Pennsylvania court upholds multimillion-dollar negligence verdict after an insurance agency failed to obtain the coverage it proposed to a commercial client.
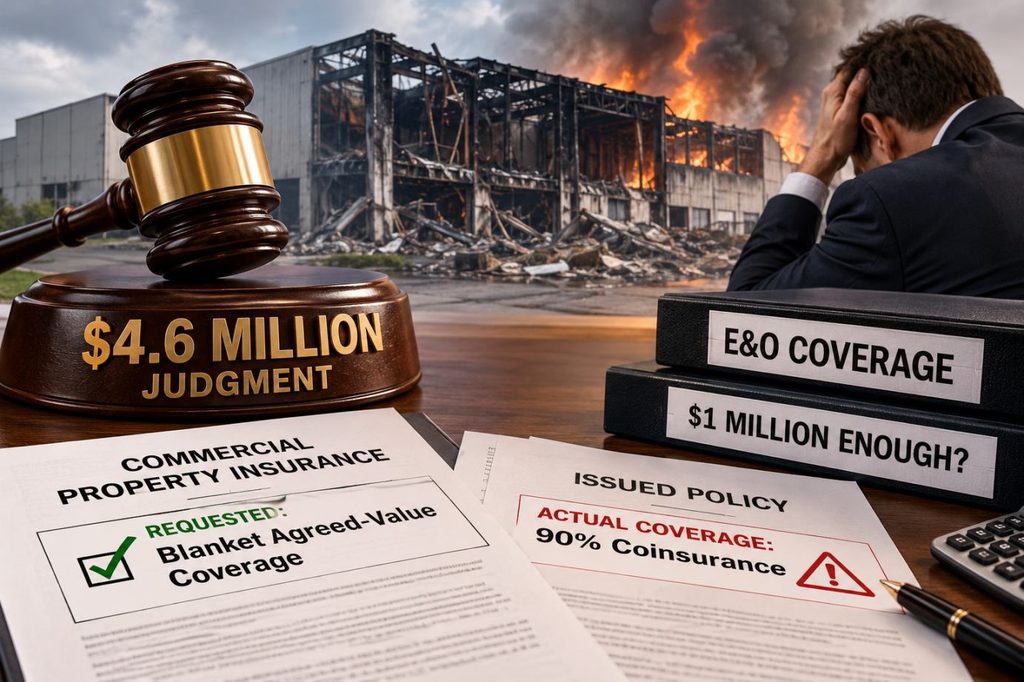
A Pennsylvania insurance agency faced a $4.6 million judgment after a manufacturing company suffered a devastating fire and discovered its insurance coverage differed substantially from what it had requested.
In Alvord-Polk, Inc. v. Strickler Agency, Inc., the Pennsylvania Superior Court affirmed the judgment against Strickler Agency on April 24, 2025, following a professional negligence lawsuit involving commercial property insurance.
How the Coverage Problem Began
Alvord-Polk, a manufacturing company with facilities in Pennsylvania and South Dakota, worked with Strickler Agency to obtain commercial property insurance through Cincinnati Insurance.
In 2017, the agency recommended blanket agreed-value coverage for the company’s buildings and business personal property, including inventory and equipment.
Blanket agreed-value coverage can be particularly beneficial for businesses operating multiple locations because it allows insurance limits to be shared across covered properties while eliminating coinsurance penalties when the agreed-value provisions apply.
Strickler submitted an application requesting $7.175 million in blanket agreed-value coverage for business personal property.
However, Cincinnati Insurance declined to provide agreed-value coverage for that property. Instead, the policy required 90% coinsurance.
According to court records, Strickler’s representatives failed to communicate this significant change to their customer. The agency’s subsequent proposal still reflected the coverage originally requested.
A Fire Exposes the Mistake
In 2019, a fire destroyed business personal property at Alvord-Polk’s South Dakota manufacturing facility.
The company expected its blanket coverage to cover the loss, valued at approximately $6.5 million.
Instead, Cincinnati Insurance applied the policy’s coinsurance provision because the company’s insured property values were substantially below their actual values.
The resulting insurance payment for business personal property was approximately $1.9 million, leaving a multimillion-dollar shortfall.
Alvord-Polk subsequently sued Strickler Agency and Cincinnati Insurance. Cincinnati settled before trial, but the negligence case against the agency continued.
The Court Finds the Agency Negligent
During the trial, testimony revealed that Strickler’s personnel had failed to recognize and communicate the discrepancy between the coverage requested and the policy actually issued.
Agency representatives acknowledged mistakes during the procurement and review process.
Strickler argued, among other things, that the policyholder had access to documents showing the actual coverage and had significantly undervalued its property.
However, the trial court found the evidence of the agency’s negligence so clear that it directed a verdict against Strickler on the issues of duty and breach.
The jury then determined that the agency’s negligence caused the company’s damages and awarded $4.6 million.
Strickler appealed, but the Pennsylvania Superior Court affirmed the judgment in April 2025. The appellate decision was designated nonprecedential.
An Important Lesson for Insurance Agencies
This case illustrates how an unnoticed coverage discrepancy can become a multimillion-dollar liability.
The problem wasn’t simply that the insured lacked sufficient coverage. The agency recommended and applied for particular coverage, failed to obtain it, and did not adequately inform the customer of the difference.
Insurance agencies should verify that issued policies match their proposals and applications, clearly communicate material coverage changes, and document those discussions.
The biggest lesson is that obtaining an insurance policy is only part of an agency’s responsibility. Ensuring the customer understands what they actually obtained can be just as important.
Could a $1 Million E&O Policy Put an Agency Out of Business?
Many insurance agencies carry only $1 million in Errors & Omissions (E&O) coverage because it meets the minimum requirements set by their carriers. However, meeting a carrier’s minimum requirement doesn’t necessarily mean an agency is adequately protected. As this $4.6 million judgment demonstrates, a single mistake can create liability far exceeding that amount. Agencies writing larger commercial accounts should seriously consider higher E&O limits, especially as property values, replacement costs, and potential litigation expenses keep rising. An agency facing a $4.6 million judgment with only $1 million in E&O coverage could be personally responsible for millions in uncovered damages, depending on its ownership structure and other circumstances. Such exposure could bankrupt the business, force the owner to lose the agency, and potentially threaten personal assets. The additional premium for higher E&O limits may be insignificant compared with the financial consequences of being underinsured.
This reinforces an important point: Carrier-mandated E&O minimums may not be enough to protect an agency’s financial future.